
Guides › Cash-Flow Forecasting for the Next 30, 60 and 90 Days
Cash-Flow Forecasting for the Next 30, 60 and 90 Days
RBTERP team · · 3 min read
How a short-term cash-flow forecast works, what goes into it, and how to use it to avoid running short of cash even when the business is profitable.
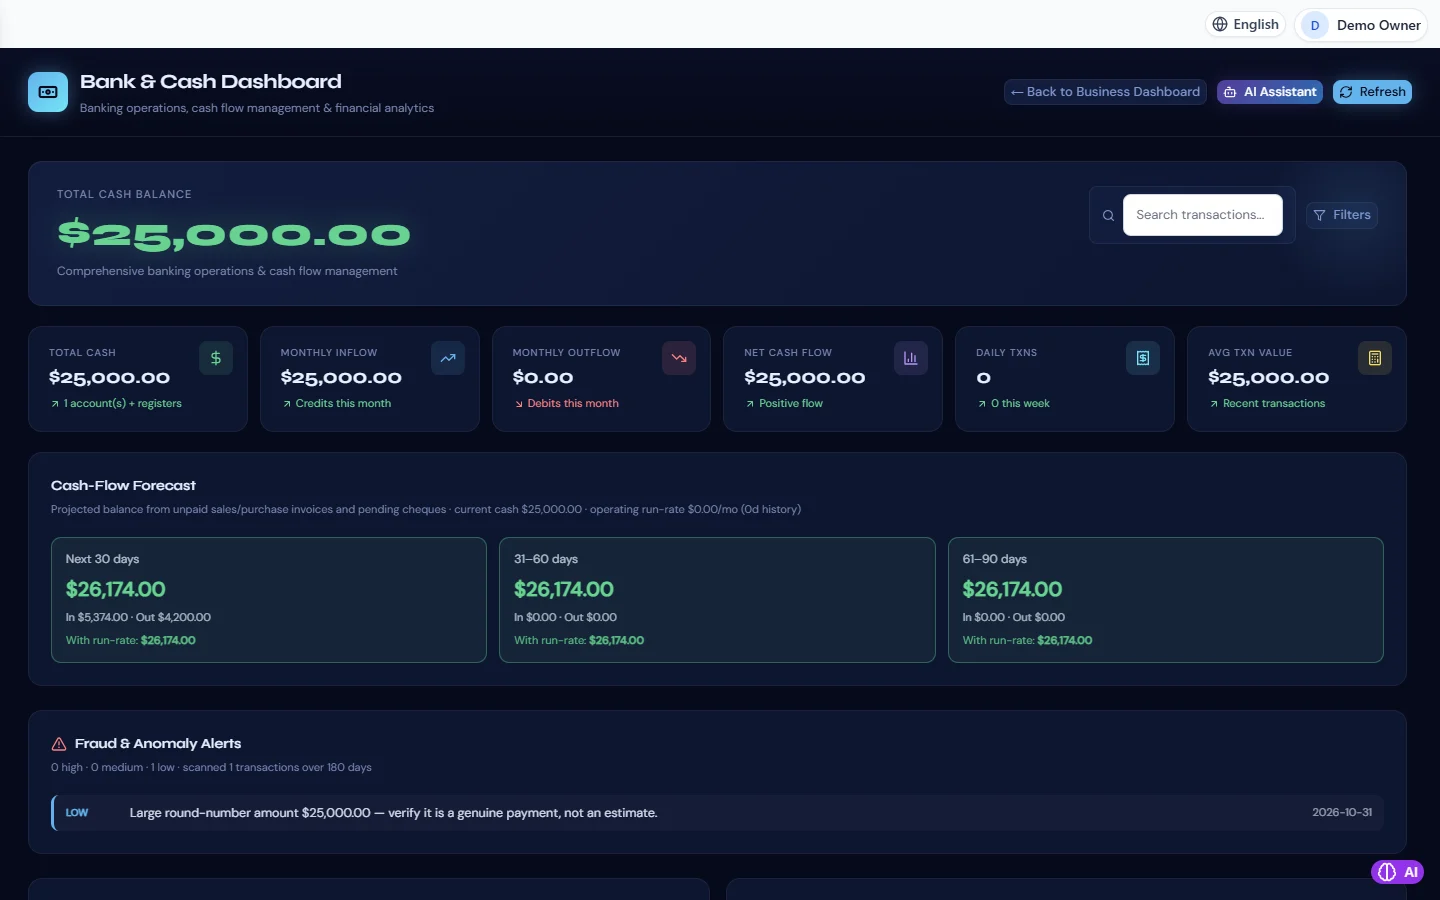
Bank & Cash in RBTERP, with a sample company and fictional data.
Businesses rarely fail because they are unprofitable on paper. They fail because they run out of cash before the profit arrives. A short-term cash-flow forecast shows the squeeze weeks before it comes, while there is still time to act.
Profit and cash are different
You can make a profitable sale today and not see the money for sixty days. Meanwhile you have paid for the goods, the salaries and the rent. Growth makes this worse: more sales mean more money tied up in stock and unpaid invoices. A forecast tracks cash, not profit.
How a forecast is built
Start with what you have, then add what is coming in and subtract what is going out, week by week or month by month:
- Opening cash: bank and cash balances today.
- Cash in: customer invoices due, based on when customers actually pay, not when they should; other expected receipts.
- Cash out: supplier bills due, salaries, rent, tax, loan repayments, cheques already written but not yet cleared.
- Closing cash: the result, which becomes next period's opening cash.
Make it realistic
- Use real payment behaviour. If a customer usually pays thirty days late, forecast it that way.
- Include the irregular items: quarterly tax, annual insurance, bonuses, loan repayments.
- Separate what is certain from what is hoped. Signed orders are not cash.
- Update it weekly. A forecast from last month describes a business that no longer exists.
What to do with it
When the forecast shows a shortfall ahead:
- Collect faster: chase overdue customers now. See receivables ageing and collections.
- Talk to suppliers about timing before a bill is overdue, not after.
- Delay discretionary spending: equipment, stock beyond immediate need.
- Arrange finance early. Banks lend more readily before a crisis than during one.
When it shows surplus cash, you can take early-payment discounts, buy stock in larger quantities, or pay down debt.
The cash-flow forecast in RBTERP
The Bank module includes a cash-flow forecast for the next 30, 60 and 90 days, built from the records already in the system:
- Unpaid customer invoices for cash coming in.
- Unpaid supplier bills for cash going out.
- Cheques not yet cleared.
Because it reads live records, it updates as soon as an invoice is raised, a bill approved or a payment recorded. Nothing is retyped into a spreadsheet.
The Bank dashboard shows it alongside total cash, monthly inflow, outflow and net cash flow, and fraud and anomaly alerts for unusual transactions.
Keep the inputs clean
The forecast is only as good as the records behind it:
- Record customer payments against the invoices they settle, or paid invoices still look like cash to come.
- Enter supplier bills when they arrive, not when you pay them.
- Reconcile the bank monthly so the starting balance is right. See bank reconciliation, step by step.
A weekly habit
Every Monday, look at the 30-day forecast and ask one question: is there any week where cash falls below what we need to pay salaries and essential suppliers? If yes, act this week. You can also have the cash report e-mailed to you each Monday; see automated report subscriptions.
This guide uses the Bank & Cash module of RBTERP: Every bank and cash account in one place, with a 30/60/90-day cash-flow forecast and alerts for unusual transactions.