
Guides › Running Monthly Payroll
Running Monthly Payroll
RBTERP team · · 3 min read
A step-by-step monthly payroll routine: what to check before the run, how payroll is accounted for, paying salaries, and correcting mistakes.
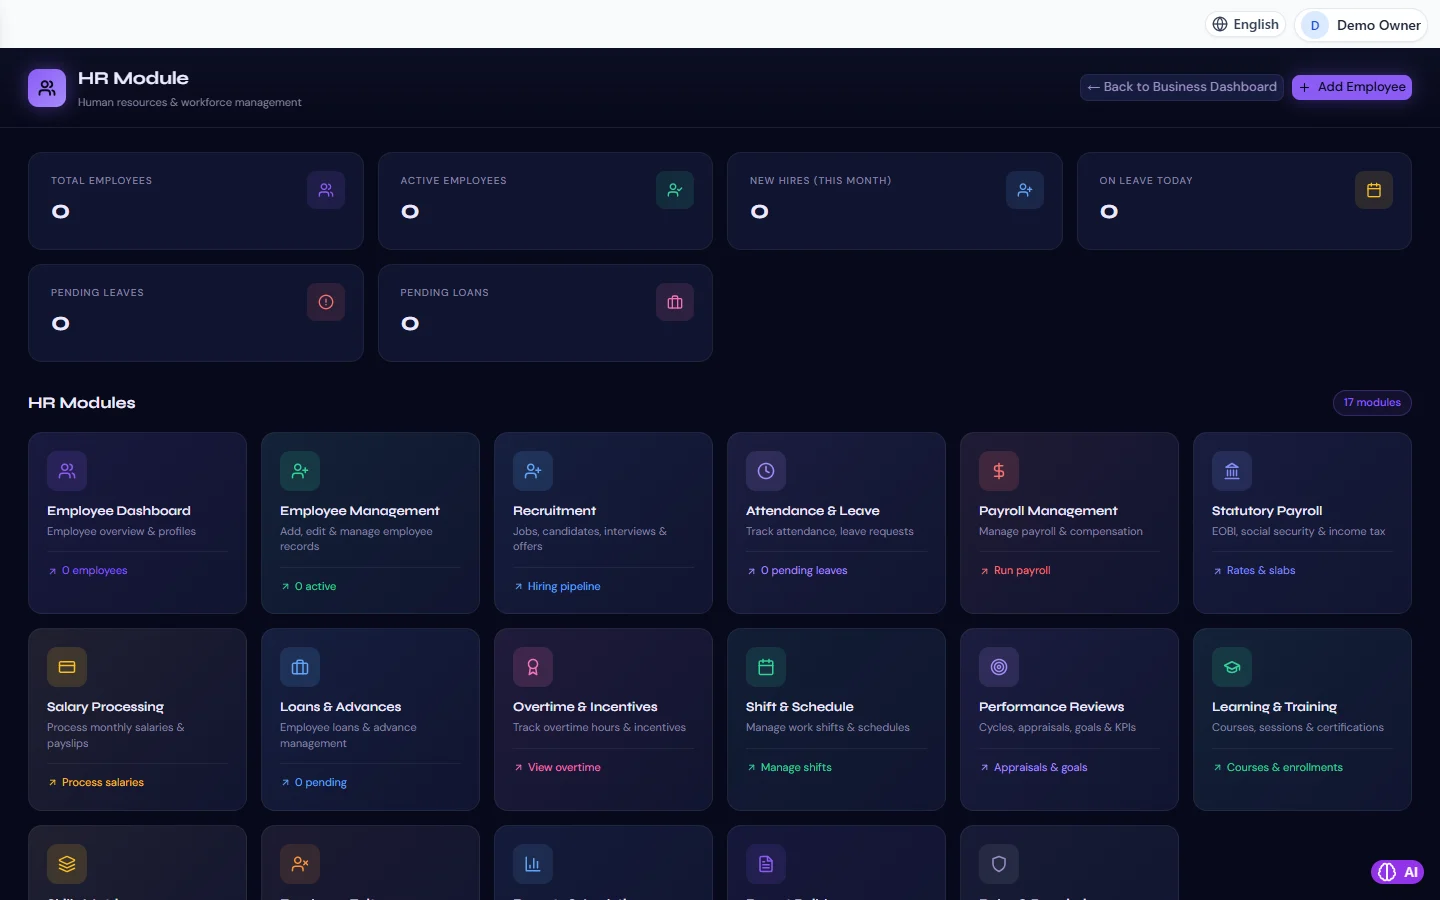
HR & Payroll in RBTERP, with a sample company and fictional data.
Payroll is the one process where every mistake is noticed immediately, by the person it affects. It is also one of the largest expenses in most businesses. A steady monthly routine makes it accurate, on time and easy to explain.
Before you run payroll
- New joiners are set up with salary, bank details and start date.
- Leavers have their last working day recorded.
- Salary changes are entered with the date they take effect.
- Leave for the month is approved, especially unpaid leave.
- Overtime and incentives are recorded and approved.
- Loan instalments due this month are known. See employee loans and final settlement.
Payroll can only be as right as these inputs.
What goes into each employee's pay
- Earnings: basic salary for the period, allowances and other components, overtime, incentives.
- Less unpaid leave, at the daily rate.
- Less deductions: income tax withheld, employee statutory contributions, loan instalments, other agreed deductions.
- Equals net pay: what reaches the employee's bank account.
Employer contributions, such as social security paid by the employer, are an additional cost to the business on top of gross pay. See statutory payroll in Pakistan.
How payroll is accounted for
Payroll is an expense of the month worked, even if salaries are paid early in the following month.
- The salary expense is recorded for what was earned.
- Net pay becomes salaries payable until it is paid.
- Each deduction becomes a payable to whoever it is owed: the tax authority, the social security institution.
- A loan instalment reduces the employee's loan balance; its interest, if any, is income.
When salaries are paid, salaries payable falls and the bank balance falls.
Check before you pay
- Compare total gross and net pay with last month. Explain any large change.
- Look at anyone whose pay changed by more than a small amount.
- Make sure nobody appears twice and nobody who left is still paid.
- Check that the bank account covers the total.
Payroll in RBTERP
- Calculated by the server, once per period. The run uses each employee's basic salary in force on the date, their own pay components, recorded overtime and incentives, leave without pay docked at the month's daily rate, loan instalments due, and the statutory rules of the jurisdiction.
- Corrections without re-running. A period is run once. A correction is an adjustment run that posts only the difference and creates a payment only for the difference.
- Books to the rupee. The run posts the expense for what was earned, credits it back for unpaid leave, credits salaries payable with the net, each deduction to its payable, loan principal to the loan receivable and loan interest to income. Every entry balances.
- Dated correctly. The payroll journal and vouchers are dated the last day of the period; the pay date dates only the payment. A period that Finance has closed refuses payroll.
- Payments through the Bank module. Salaries move the bank account and appear in its register under the HR document that paid. A salary goes only to an employee with a bank account on file, and only from an account that covers the batch. A failed payment can be put back and paid once the cause is fixed. Nobody is paid twice.
- Payslips are produced for each employee.
After payroll
- Send payslips.
- Pay statutory deductions to the authorities by their deadlines.
- Reconcile the salaries payable and deduction accounts: after payment they should be back to zero, or to exactly what is still due.
This guide uses the HR & Payroll module of RBTERP: Seventeen HR areas from recruitment to payroll, including statutory payroll with EOBI, social security and income tax.