
Guides › Employee Loans, Advances and Final Settlement
Employee Loans, Advances and Final Settlement
RBTERP team · · 3 min read
How to manage salary advances and staff loans fairly, recover them through payroll, and settle everything correctly when an employee leaves.
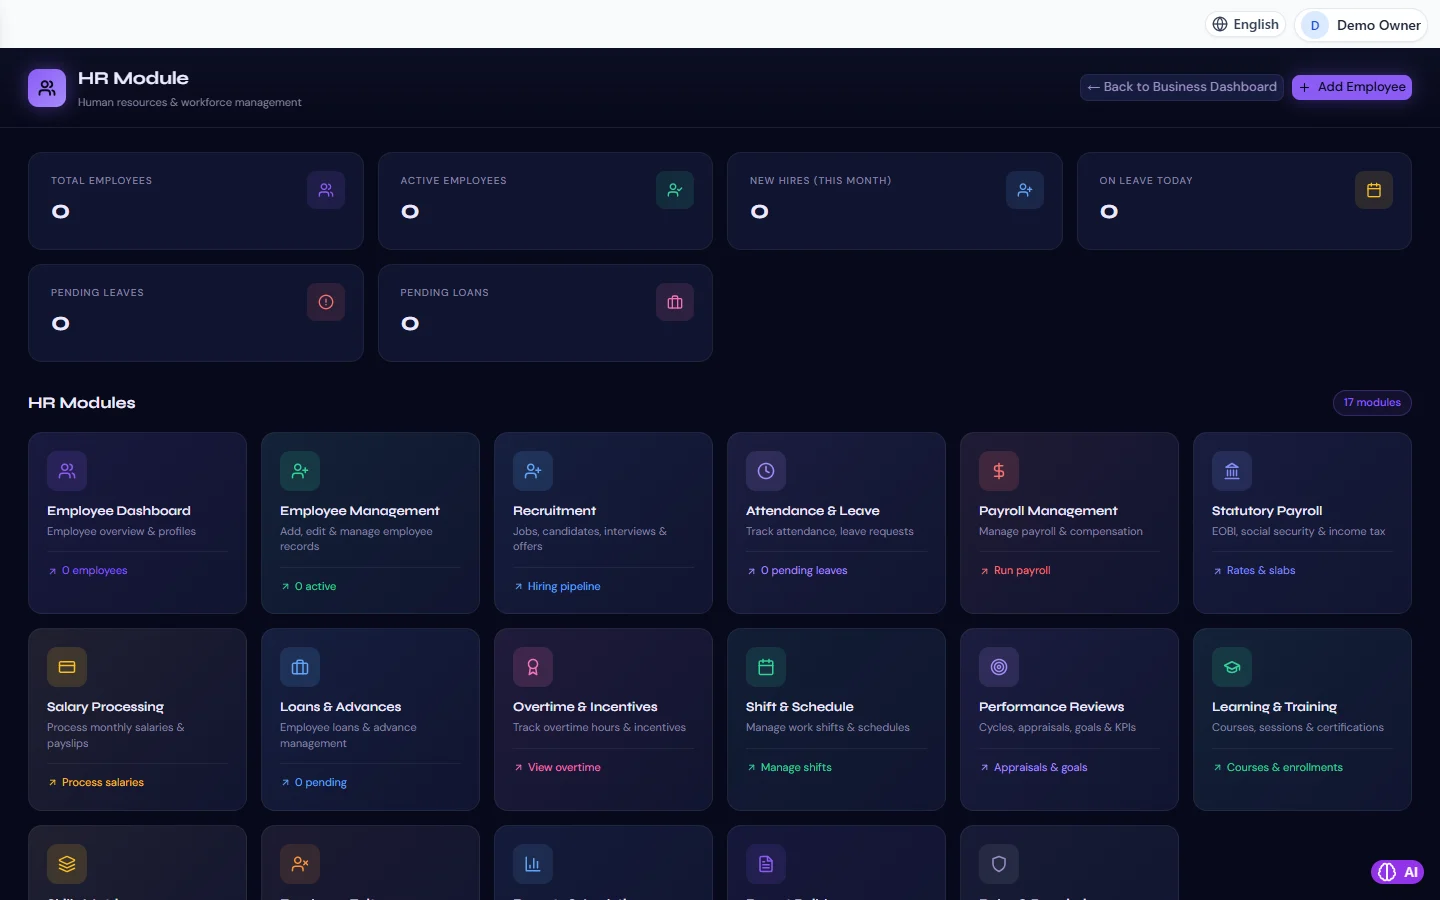
HR & Payroll in RBTERP, with a sample company and fictional data.
Many employers help staff with advances against salary or longer loans. Handled informally, these create confusion about who owes what, especially when someone leaves. A written agreement, a schedule and recovery through payroll keep everything clear.
Advance or loan?
- An advance is part of next salary paid early, recovered in full from the next payroll.
- A loan is repaid over several months in instalments, sometimes with interest.
Both are money the employee owes the business, an asset in your books, until recovered.
Put it in writing
For every loan, agree in writing:
- The amount and the date it is paid.
- The number of instalments, and the amount of each.
- Any interest, and how it is calculated.
- That instalments are deducted from salary.
- What happens if the employee leaves before repaying: recovery from the final settlement.
Check your country's rules on how much can be deducted from wages each month.
Recovering through payroll
Deduct each instalment in payroll, so recovery is automatic and visible on the payslip. If an employee faces hardship, you may agree to change one month's instalment or carry it forward. Record that change in the schedule, so the total still adds up.
Keep the books right
- Paying a loan: the employee loan receivable goes up; the bank goes down.
- Each instalment: the loan receivable goes down by the principal; any interest is income.
- At any time, the loan balance should equal what was lent minus principal recovered.
Final settlement
When someone leaves, everything between you is settled once:
- What you owe them: salary to the last day, unused leave if your policy pays it, gratuity or end-of-service benefits where applicable, and other dues.
- What they owe you: loan balances, advances, unreturned property.
- The net: paid to them, or in rare cases recovered from them.
Prepare a settlement statement listing every item, and have the employee sign it.
Loans and settlements in RBTERP
- Loans and advances are part of the HR module. Paying a loan out moves money through the Bank module, so the bank account, its register and the loan stay in agreement.
- Repayment on schedule: the first instalment falls due one month after the start. Each instalment is its principal plus its interest, with recovered interest first.
- Changing a month: changing a month's instalment or carrying it forward moves principal and interest together, so the loan is always the amount lent and the interest always the interest scheduled.
- Through payroll: instalments due in the month are recovered in that month's payroll run, with the principal credited to the loan receivable and the interest to interest income.
- Final settlement, once and all-or-nothing: RBTERP works out the figures; outstanding loans are recovered oldest first, with their interest as income; the employee is marked as gone and the exit is completed. Deleting a settlement reverses every part of it.
- End-of-service rules such as gratuity come from the country pack.
- Closed periods: a loan payment or settlement dated in a month Finance has closed is refused.
- Undoing a payment: taking back a loan payment puts the money back in the bank, unless the bank has already reconciled that payment.
A sensible policy
- Set a maximum, such as one month's salary for advances.
- Do not issue a new loan while an old one is outstanding.
- Review outstanding loans monthly, alongside payroll. See running monthly payroll.
This guide uses the HR & Payroll module of RBTERP: Seventeen HR areas from recruitment to payroll, including statutory payroll with EOBI, social security and income tax.